LOCATION & IDENTITY
A sense of place
Located in Wahat Al Jabal Al Sharqi, Al Hamra, the concept targets local visitors, families and tourists seeking hospitality connected to its surroundings.
HOSPITALITY ROOTED IN PLACE
SABAG brings coffee, food and terrace seating to Eastern Mountain Oasis in Al Hamra. Following the site award, contract signing and handover, the project is preparing for structural drawings and initial construction. Explore the asset, its progress and its funding needs.
CURRENT PHASE FUNDING30,000 OMRFrom investors and partners for initial construction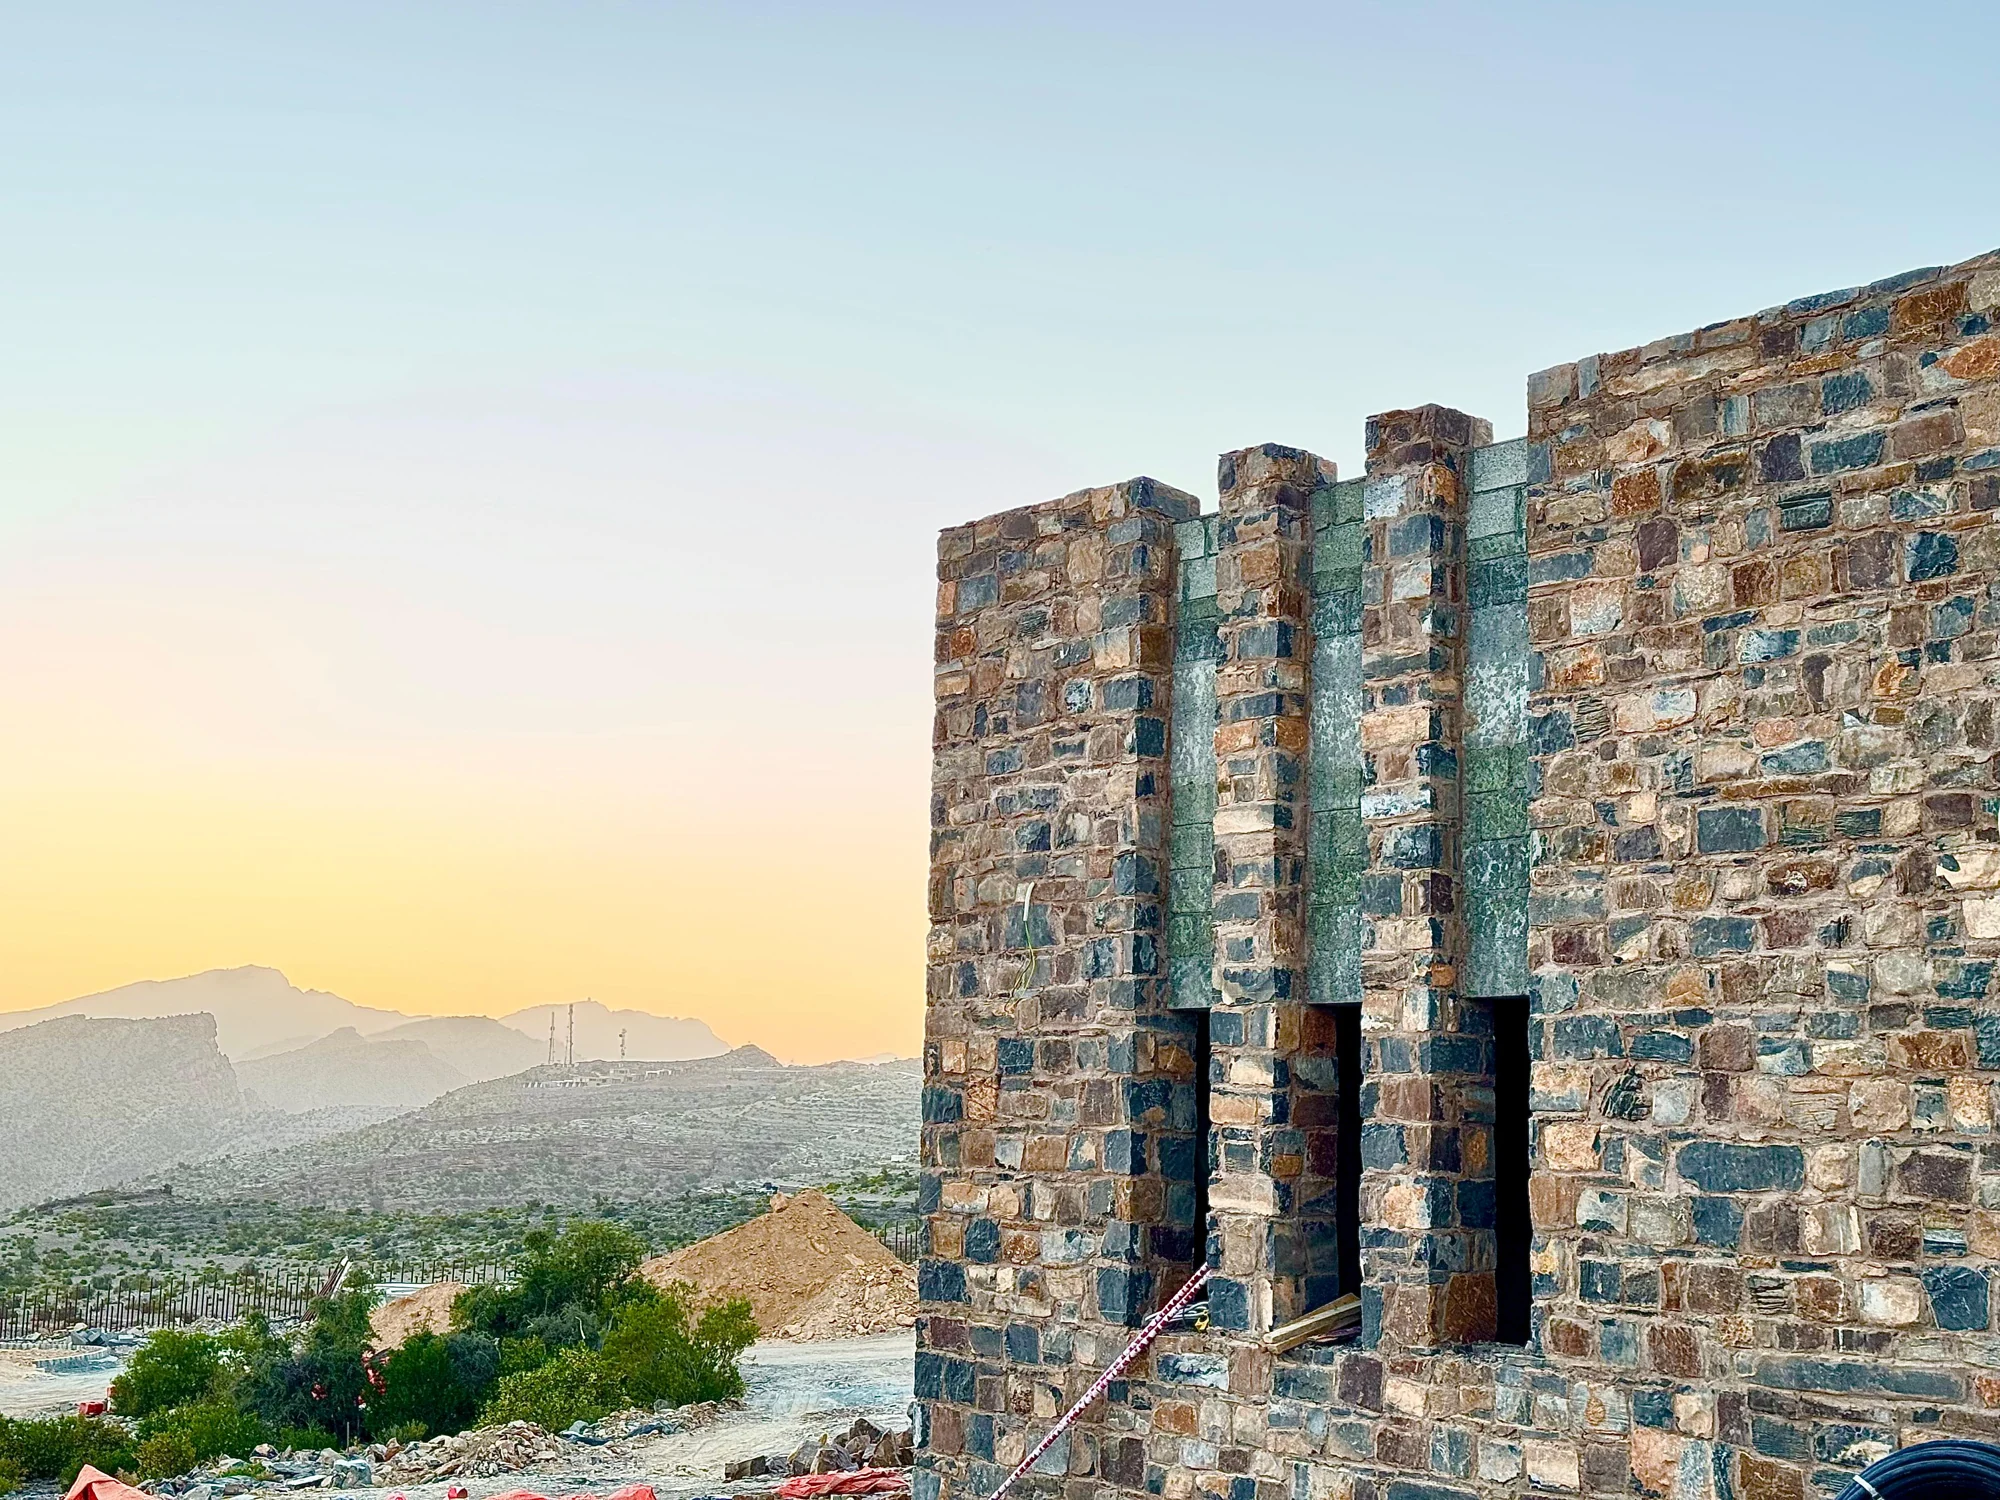 PROJECT SITE PHOTOGRAPH
COFFEE · FOOD · PLACE
Wahat Al Jabal Al Sharqi · Al HamraAreas from the drawings dated 12 August 2026; they do not represent the land area or total outdoor seating area.
01 / OPPORTUNITY
SABAG combines its setting with a varied hospitality offering: a place to visit for coffee, a meal or time on the terrace.
LOCATION & IDENTITY
Located in Wahat Al Jabal Al Sharqi, Al Hamra, the concept targets local visitors, families and tourists seeking hospitality connected to its surroundings.
VARIETY OF EXPERIENCE
Specialty coffee, breakfast and meals, with indoor and terrace seating. These varied uses shape the visitor experience and guide menu and concept development.
DESIGNED FOR SERVICE
The drawings combine on-site seating, takeaway and drive-through service, supported by a kitchen, coffee bar and service facilities.
Project photographs archived since August 2026. Capture dates are undocumented; these images do not establish current construction progress.
THE SABAG IDENTITY
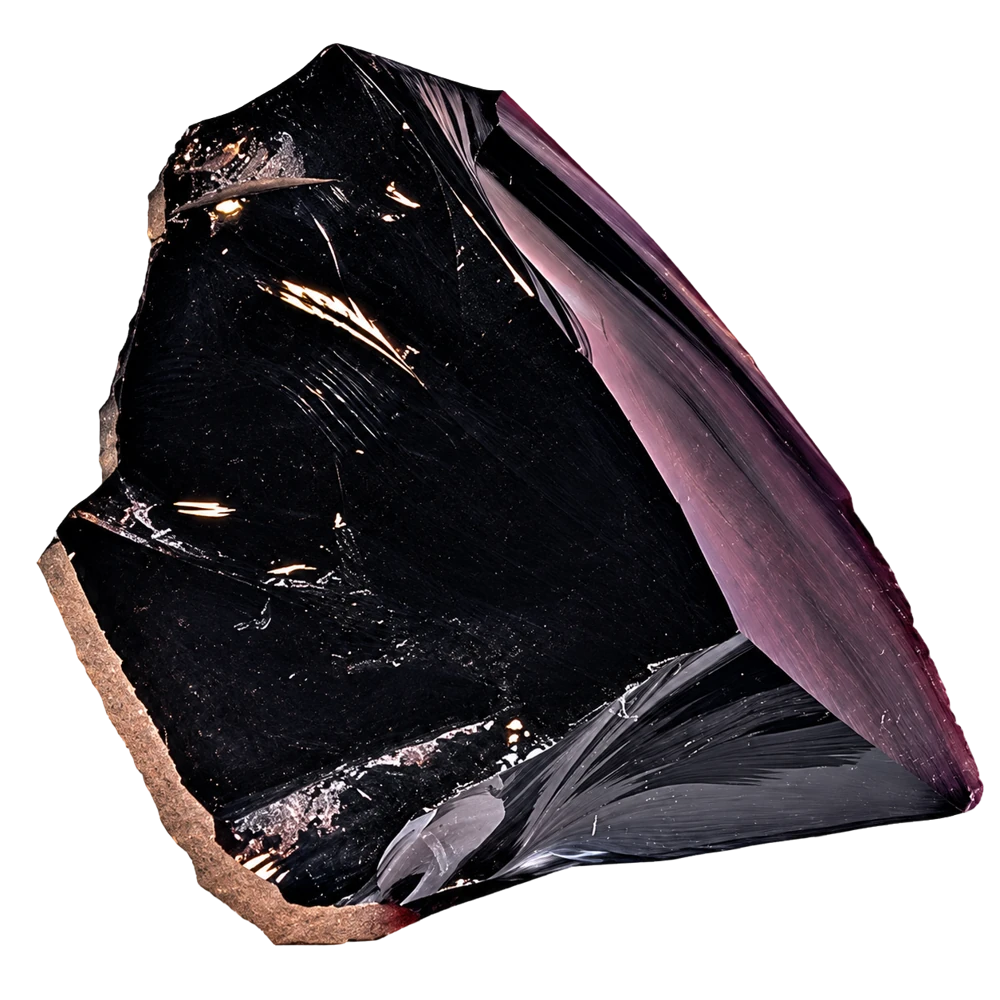
The SABAG identity draws on the depth and sheen of its namesake stone, alongside the quiet of the mountain and the warmth of hospitality.
BEHIND THE NAME
The name evokes the dark colour and glassy sheen of the stone depicted in the identity document. In the brand story, this visual depth becomes an expression of calm, distinction and a memorable presence.
At the Eastern Mountain Oasis, that inspiration meets an open landscape, coffee and food. This connection to place shapes the experience the brand aims to offer its guests.
The identity document explores the Arabic letters س، ب، ج and their visual relationship to SABAG. The name and logo retain the forms shown in the original document.
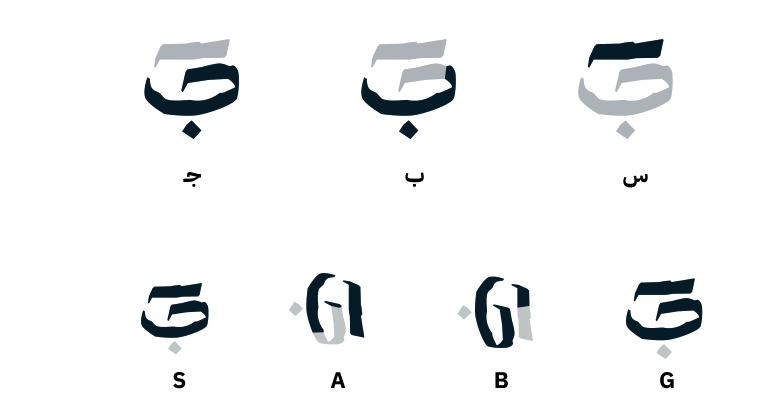
From the logo to the guest experienceThis direction informs the development of menus, packaging, signage and digital channels, bringing the café’s touchpoints into a consistent visual language.
IDENTITY DEVELOPMENT & OWNERSHIP
Hospitality Technologies is responsible for developing and funding the visual identity. Ownership of the SABAG identity and brand belongs to the hospitality company.
Operator responsibilitiesTHE INVESTOR’S PARTICIPATION
Investor participation concerns the project assets under the partner agreements. Site usufruct rights remain with Technological Leadership Sustainable LLC (TLS), separately from brand ownership.
Asset and investor rightsUse of the brandThe operating agreement is to govern the scope and duration of brand use, including arrangements at the end of the operating relationship. Asset participation does not automatically confer ownership of the brand or the hospitality company.
THE 3D DESIGN
32 views explore the café architecture, terraces among the rocks, arrival details and evening atmosphere.
Building & setting Page 3 of 32
These are design visualisations from the shared file, not photographs of completed works or evidence of final approval.
Shared design file · Received 14 September 2026
02 / THE ASSET
Technological Leadership Sustainable LLC (TLS) holds the site investment and use rights, having won the competition and signed the contract. Investment supports the development and equipment of the SABAG asset; partner agreements define participation rights.
Site context, ground-floor layout and rooftop uses — design references dated 12 August 2026.
Source: TheHome drawings · 12 August 2026
The proposed building within the wider oasis
Drawings are design references, not evidence of regulatory approval or completed construction. The site plan shows the wider setting and does not establish SABAG ownership of that whole area.
A functional summary of the drawings, not a scale architectural plan.
FOCUS OF THIS PAGE
TLS holds the site investment and use rights. Investors participate in funding, developing and equipping the asset and monitoring its performance. Partner agreements document their interests and distribution rights.
CONTRACTED OPERATIONS
Develops the hospitality experience and manages the café for 25% of revenue under the updated presentation basis. The proposed scope covers management, menu, people, quality, marketing and financial controls. The operator and its branches remain separate from the SABAG asset; obligations are documented in the operating agreement. Hospitality Technologies funds and develops the visual identity and owns the SABAG identity and brand.
The site contract has been signed, the guarantee paid and cheques submitted. Al Hamra Municipality handed over the site in September 2026. TLS holds the site-use rights; separate agreements govern partner interests and distributions.
THE ASSET’S CONTRACTUAL BASIS
Technological Leadership Sustainable LLC won the site competition after submitting its feasibility study, then signed the investment contract, paid the guarantee and submitted the cheques. The site was received from Al Hamra Municipality in September 2026. TLS holds the site investment and use rights within the contract’s scope.
Period stated in the contract copy: 1 August 2026 – 31 July 2041. The contract’s 196 m² is site area; drawings show 215 m² of total built floor area across ground and upper levels.
Develop and operate a restaurant and café within the allocated site. Outdoor seating requires coordination with the Governorate and approved drawings.
Clause 2Complete construction within 10 months of contract commencement and operate upon completion, with the required permits and standards.
Clauses 6 and 7TLS is the named contracting investor. Assignment or transfer requires prior written consent; investor participation does not automatically transfer the site rights.
Clause 7If the completed project or part is leased to a third party, leases must be documented with the municipality. TLS remains responsible to the Governorate.
Clause 10Financing secured by the contract is restricted to one financing entity and this project only. This applies when structuring the TLS loan.
Clause 6Renewal is not automatic. A written request is required three months before expiry; the Governorate may decline renewal or convert to a market-rent lease. Breaches may lead to termination.
Clauses 7 and 8| Period | Instalment | Period or annual total |
|---|---|---|
| Aug 2026 – Jan 2028 | Rent-free | 0 |
| Feb and May 2028 | 240 per instalment | 480 |
| Aug 2028 – Jul 2031 | 240 quarterly | 960 annually |
| Aug 2031 – Jul 2036 | 300 quarterly | 1,200 annually |
| Aug 2036 – Jul 2041 | 360 quarterly | 1,440 annually |
| Total consideration over 15 years | 16,560 | |
Instalments fall in February, May, August and November. Project management confirms guarantee payment and cheque submission; contractual guarantee-renewal requirements remain applicable. Site consideration is distinct from project development cost and funding.
The Governorate’s letter of 12 July 2026 confirms contracting with TLS. The 14 September 2026 management update confirms contract signing, guarantee payment, cheque submission and site handover. Term, area and payment highlights were prepared from the available review copy, clauses 2–10 and annex 2, and require reconciliation with the signed version. Site-use rights do not imply ownership of the land itself.
CAFÉ OPERATING MODEL
Hospitality Technologies and Operations manages SABAG from opening readiness through daily service, within an approved budget and authority framework, with reporting that lets asset owners monitor performance.
Proposed scope for the operating agreementDevelop and price the menu, standardise recipes and portions, and organise service around the SABAG identity.
Deliverables: costed recipes, approved menu, preparation and service standards, and an opening-readiness plan.
Recruitment and selection, training, shift planning, branch-manager supervision and team performance management.
Deliverables: staffing structure, role descriptions, training records and daily opening/closing checklists.
Hygiene, food storage and temperatures, separation, allergens and coordination with the relevant authorities.
Deliverables: safety and inspection logs, preventive-maintenance follow-up, corrective actions and incident reporting.
Supplier selection within delegated authority, price comparisons, receiving controls, stock management, waste and recipe-cost tracking.
Deliverables: purchasing and stock records, variance and expiry tracking, and invoices reconciled to deliveries.
Manage content, promotions and digital channels, coordinate bookings and events, and respond to guest feedback.
Deliverables: a monthly marketing plan, complaint-resolution records and campaign sales-effectiveness reporting.
Manage POS records and daily reconciliation, prepare budgets, and track expenses, cash flow and liquidity requirements.
Deliverables: sales, expense, inventory and cash reports, with variance explanations and corrective actions.
Managing a task and funding its cost are separate responsibilities. This proposed allocation prevents duplicate charges and the transfer of other branches’ expenses to SABAG.
| Cost category | Proposed funding source | Responsibility boundaries |
|---|---|---|
| Management and central services | Included in the 25% fee | Central management and supervision, HR and procurement administration, internal training, reporting and routine content marketing. No additional central charge for these services. |
| Identity and brand development | Hospitality Technologies | Hospitality Technologies funds and develops the identity and logo, and owns the SABAG identity and brand. Identity development is not charged to the asset development budget. |
| Direct café team | Café operating budget | Branch manager, barista, kitchen and service payroll, benefits and direct hiring costs. Managed by the operator; the agreement identifies the legal employer and its statutory obligations. |
| Supplies and daily expenses | Café operating budget | Ingredients, packaging, utilities, cleaning, pest control, routine maintenance and payment/delivery commissions, supported by records and within budget. |
| Campaigns, systems and specialists | Separately pre-approved budget | Paid advertising, branch-specific software subscriptions, and external inspections, training or advisers; no extra commitment or charge without written approval. |
| Development, construction and fit-out | Asset development budget | Construction, capital equipment and initial asset-specific consultancy under their approved contracts and budgets. The operator coordinates technical input; these contracts are not assumed covered by the fee. |
| Usufruct, finance and insurance | Asset and obligations budget | Usufruct obligations, debt service, asset renewal and insurance as allocated in the relevant agreements. Usufruct rights remain with TLS. |
The projection retains study expenses until they are reconciled line by line with this scope. Any verified overlap is removed when the budget is approved; no savings are assumed in advance.
25% × recorded SABAG sales after discounts and refunds, excluding VAT and sums collected for third parties. Calculated before payroll, ingredients, utilities and payment/delivery commissions.
Includes café sales, takeaway and related services. Loans, investor contributions and asset disposals are excluded. Platform sales are reconciled to statements before commissions where SABAG is the seller of the service.
Monthly settlement from reconciled POS and accounting records. Deposits and gift cards are excluded until revenue is recognised, with no double counting on redemption. Accruals and subsequent refunds are governed by the agreement.
The project owner selected the rate for this presentation; it is not a recommended market benchmark or evidence of an executed contract. Fee taxation and commencement are to be confirmed; pre-opening work requires a separately approved budget.
Channel sales, cash/card reconciliation, product availability, and safety and incident records.
Order count and average transaction, waste and stock variances, labour hours, complaints and corrective actions.
Sales and expenses against budget, the 25% fee reconciliation, cash flow and the next-month plan. Proposed delivery: within 10 business days of close.
Service, waste, ingredient and labour-cost targets are agreed before opening, based on the approved menu, capacity and budget. These are proposed reporting commitments, not achieved operating results.
Separate project accounts and records, data access for authorised owners and audit rights. Approved budgets, purchasing and discount limits, with approval for overruns and material commitments.
No extra management, brand or incentive fee for included services. Related-party purchases, margins and supplier rebates must be disclosed and approved; other branches’ expenses are not allocated to SABAG.
Define safety, insurance and negligence responsibilities, breach remedies and termination. No borrowing, encumbrance or transfer of asset rights without the necessary owner and authority approvals.
Inventory and transfer of assets, records, digital accounts and project data according to their access rights, with a transition plan. Ownership of the SABAG identity and brand remains with Hospitality Technologies; brand use, recipe rights and transition arrangements require a separate clause.
The references inform management, control, safety and inventory responsibilities. Cost allocation and reporting deadlines are proposals for SABAG, to be aligned with Oman requirements in the agreement. They do not establish operator certification or validate a 25% market fee.
03 / INVESTMENT
The current phase requires OMR 30,000, expected from investors and partners to start initial construction. The study’s total investment and the proposed overall funding structure are set out below.
CASH REQUIRED NOW
30,000 OMRTargeted from investors and partnersMOVING INTO INITIAL CONSTRUCTION
Following site handover, structural drawings and excavation are the next steps. This funding supports the initial construction works.
A cash requirement for the current phase; contributions are recorded upon receipt. Total study funding and the proposed funding structure follow below.
Forecasts for five years from the start of operations.
Year 1 selected: OMR 428,745 projected revenue. This selection also updates the asset-surplus model. Explore the effect of operator fees ↗
| Operating year | Revenue | EBITDA | Project net profit |
|---|---|---|---|
| 1 | 428,745 | 178,420 | 134,704 |
| 2 | 486,212 | 209,554 | 161,688 |
| 3 | 544,785 | 228,163 | 178,049 |
| 4 | 604,482 | 249,120 | 196,347 |
| 5 | 665,317 | 273,807 | 217,925 |
The original report assumes 400 m² indoors/outdoors, 139 seats and a 25-year lease horizon. The site contract copy specifies 196 m² and 15 years; drawings show 215 m² total built floor area. Capacity, areas, rent and forecast horizon require alignment with the contract. Report indicators do not extend site rights.
Indicators are sourced from Biza Advisory’s Sharqah Terrace (Shurfat Al-Sharq) report, pp. 5, 33, 43–48 and 54–55. Profit and payback refer to the original scenario; asset surplus after operator fees and financing is assessed separately.
Original study forecasts before revised funding and operator fees; distributions are not guaranteed. Areas, site-use term and rent require alignment with the contract; details and sources are above.
Through SME Development Authority loans, under the proposed assumption.
99,970 OMRPartner contributions to the asset’s development and equipment.
99,970 OMREach source provides 50% of the OMR 199,940 study total, including later additions. This funding assumption does not establish loan approval, received contributions, ownership or distribution percentages.
| Phase | TLS via loan | Asset partners | Total |
|---|---|---|---|
| Initial funding | 94,937 | 94,937 | 189,874 |
| Later additions | 5,033 | 5,033 | 10,066 |
| Total | 99,970 | 99,970 | 199,940 |
This is a phase-specific cash requirement for initial construction. Contributions are recorded upon receipt and expenditure tracked within project funding.
04 / RETURNS
Asset surplus is calculated after operating costs and operator fees under the financial model. Debt service, other obligations and the owners’ agreement then determine distributable amounts.
Coffee, food, takeaway and other sales included in the agreement.
One operator fee of 25% of eligible revenue. Direct expenses are paid from the café budget under the responsibility schedule.
Surplus after fees, then debt service, tax, capital additions and reserves before distribution under the ownership agreement.
25% of café sales after discounts and refunds, excluding VAT and amounts collected for third parties, before operating expenses. There is no net-profit participation. The revenue base, monthly settlement and included scope are documented in the agreement.
The loan schedule, financing cost, grace period and repayment responsibility, followed by TLS and partner rights and surplus-distribution percentages. The 50/50 funding assumption does not establish those rights.
Visitor volume, average spend and how they vary across the year.
Construction and equipment scope, prices and required contingency.
Permits, procurement, recruitment and the start of revenue generation.
05 / PROGRESS
Contracting, preliminary design and site handover have progressed. Structural drawings and excavation are next, while the hospitality experience is developed alongside the asset.
Project management update · 14 September 2026
LATEST COMPLETED MILESTONE
The site was received this month, following contract signing, guarantee payment, cheque submission and submission of preliminary drawings.
View asset rights and contract highlights ↗NEXT PHASE
Begin structural drawings, followed by excavation and initial construction. This step is supported by a target of OMR 30,000 from investors and partners.
View phase funding ↗Technological Leadership Sustainable LLC submitted a feasibility study, competed for the site and won the award.
Related details for this milestoneThe site contract was signed, the guarantee paid and the cheques submitted.
Related details for this milestoneThe initial site drawings were submitted. Drawings and 3D design views are available to explore.
Related details for this milestoneHospitality Technologies and Operations has begun contracting procedures with consultants from Saudi Arabia and Dubai to develop the menu and hospitality concept.
Related details for this milestoneA specialist company has been contracted to develop the project’s brand. Hospitality Technologies is responsible for identity development, its cost and ownership.
Related details for this milestoneThe site was received from Al Hamra Municipality during September 2026.
Related details for this milestonePrepare structural drawings and move towards excavation and initial construction, supported by the phase’s funding requirement.
Related details for this milestone06 / OWNERS’ SPACE
A private space is being prepared for SABAG asset owners, bringing together contributions, documents, decisions and updates according to each owner’s access.
Committed, paid and outstanding amounts, tied to the asset ownership register.
The decision, options, financial and timing impact, and supporting document.
Progress and budget, followed by performance and distributions once operating.
This public page does not contain individual investor data or private documents.
07 / REFERENCES
Explore the design, drawings and rights summary. Detailed contractual and financial records will be available through the owners’ space once private access is activated.
Results: 12
TLS rights, contract term, area and obligations
Areas and the arrangement of hospitality and service facilities
32 views of façades, terraces, entrances and lighting
Asset budget and revenue, cost and funding assumptions
25% revenue fee, service scope and cost allocation
Dated progress, expenditure, commitments and decisions
Original file · name, symbol construction and identity colours · 4.4 MB
Design reference · 12 August 2026
Design reference · 12 August 2026
Design reference · 12 August 2026
Original file · 32 pages · 127.3 MB
Proposed models for review before contracting (Arabic)
OMR 30,000 is expected from investors and partners for initial construction. This is the current phase’s cash requirement; partner agreements and the funding register document contributions and rights.
This overview concerns the SABAG asset. The hospitality company is a contracted operator that may run multiple branches. Its founders’ interests and capital do not represent investor interests in the SABAG asset.
Hospitality Technologies funds and develops the visual identity and owns the identity and brand. Investor participation concerns the project assets under the partner agreements; use of the brand is to be governed by the operating agreement.
The Governorate’s letter confirms the investment contract with TLS. The available contract copy specifies 15 years from 1 August 2026 to 31 July 2041 and a 196 m² site. Partner agreements establish investor interests and distributions; site-use rights do not mean ownership of the land itself.
Report indicators describe the original scenario. The updated view calculates asset surplus after hospitality fees under the operator-fee model; owner distributions require loan terms and a surplus-distribution agreement. 50/50 funding does not imply 50/50 ownership or distributions.
Owner reports will connect actual progress with the programme, budget and forecast cost to complete, identifying required decisions. These reports need verified delivery and financial data and the activation of private access.